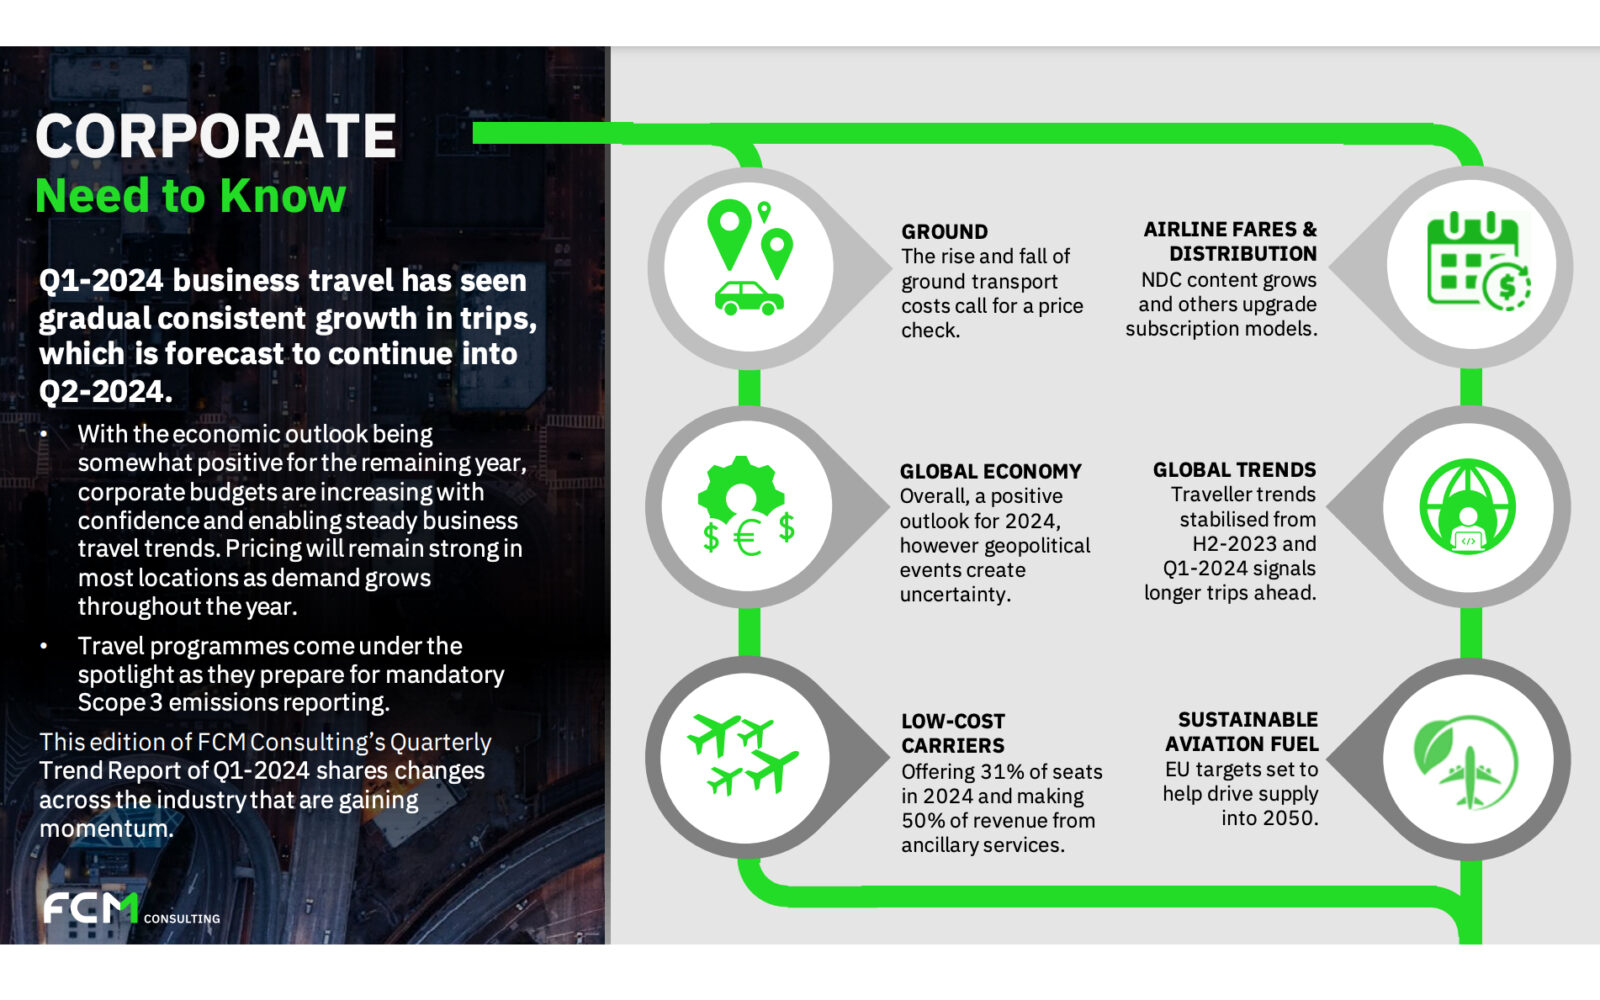
Q1-2024 business travel has seen consistent growth in trips, which is forecast to continue into Q2-2024, according to FCM Consulting’s latest Global Quarterly Trend Report*. The report showed that on average, globally, ticket prices in economy were 11% above the same month in 2019 prior to the pandemic. But, encouragingly, flight costs in the same class had dropped 16% when compared to January 2021. APAC director of FCM Consulting Felicity Burke said that pricing for travel remained strong as demand incrementally grows in 2024. “Global inflation is estimated to be at 5.9% in 2024, unemployment rates are trending lower, and consumer confidence is returning once again,” Burke said, quoting an IMF report. “Generally, the global economy has been resilient against increases in interest rates, and with the economic outlook being somewhat positive for the remaining year, corporate budgets are increasing with confidence and enabling steady business travel trends. “Pricing will remain strong in most locations as demand grows throughout the year, but it needs to be kept in mind that several geopolitical conflicts will continue to bring a level of uncertainty to the global economy.” Burke said the report highlighted that stable booking volumes in Q1-2024 meant that corporate travel demand remained steady and there was now less guesswork for the industry (airlines, hotels, and car hire) regarding that demand – they could now rely on consistent volumes. “Travellers continue to tightly manage budgets for the remainder of the year with early bookings and more days away. The average advanced booking days have increased to 23.3 and the average days away have also lifted to 4.4 – unsurprising, given the continued business ‘bleisure’ trend,” she said. “Monthly seats offered from May to December 2024 have been forecasted to an average of +3.6% (+17.8m) above 2019 monthly averages, with 2024 scheduling continuing to signal supply confidence across five of the seven global regions. “The forecast for seats offered across top corporate global airlines in 2024 is set to be 6% above 2019, with the number of flights offered down 1% – top corporate airlines globally show that low-cost carriers (LCC) are also performing well. “Interestingly, LCCs will represent 31% of global seats offered in 2024. That is a 1% increase versus 2019 – with 28% of all flights offered also being on an LCC carrier, again a rise of 1%.” *The FCM Consulting quarterly trend report draws on global data sourced from FCM Travel and Flight Centre Travel Group corporate booking data for travel from January to March 2024 (Q1-2024). The report uses Cirium aviation schedule data as at 16 April 2024. Airfare pricing variations exclude all taxes.
Corporate travel budgets gain altitude on economic outlooks and confidence
Comments
Comments are closed on this post.
Trending
Bahrain wins bid for FDI World Dental Congress 2028
1 week ago
Auckland wins international chemistry conference ICCC50
1 week ago
LIONS evolves global model with launch of regional platforms in North America, APAC and MENA
1 week ago
Ras Al Khaimah TDA signs understanding with Emirates to drive visitor arrivals
1 week ago
Radisson Hotel Group and GDS-Movement launch roadmap to close sustainability action gap
1 week ago
Destinations International launches new advocacy research
1 week ago
Penang International Travel Exchange set to return, bringing 100 buyers back in October
1 week ago
Advertisement
Essential Reads
New EIC study finds business events contribute US$1.8 trillion to global GDP
Analysis
Washington DC bucks trend of US tourism decline with record visitor spending
North America

A look back at November’s IBTM and how event formats are “festivalising”
IBTMWorld

US airports face potential closures amid government shutdown
Business Travel
The countries with the highest business travel spend in the world
Business Travel